Capture inflows on your real pay dates
Salary, freelance deposits, and allowances are placed on the dates they land so the monthly spending plan mirrors cash availability.
Craft-led household budgeting: we shape monthly spending plans that respect your income rhythm, fixed obligations, and the way your family actually shops and saves.
 Monthly categories sketched before numbers are finalized
We group groceries, transport, school fees, and debt service into envelopes you can explain to a partner in one sentence.
Financial planning consultations here focus on household budgeting mechanics: which bills are immovable, which subscriptions drift, and where a monthly spending plan needs guardrails instead of vague targets.
Personalized planning sessions walk through your pay cycle, not an idealized calendar month, so carry-over balances and irregular income are handled explicitly.
Explore consultation focusHousehold financial management is a craft of timing — due dates, seasonal school costs, and the week groceries cost more because guests arrive.
Plans are built so you can reallocate without abandoning the whole budget when electricity spikes or medical copays appear.
We document trade-offs in plain language: if dining out rises, which discretionary line absorbs it, and what minimum savings still holds.
This is financial planning and management for homes, not corporate treasury — every line should survive a conversation at the kitchen table.
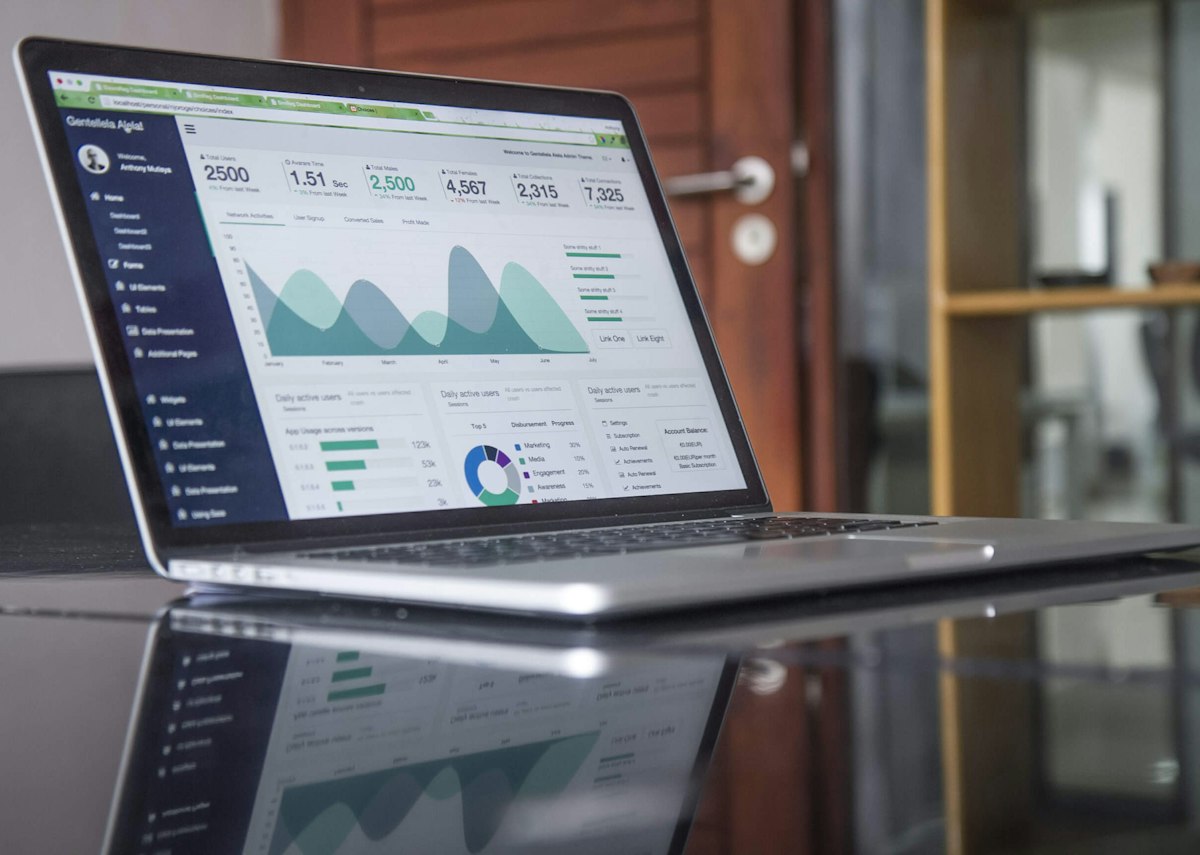
Each pass produces a tangible artifact you keep — lists, calendars, or category caps — before any forward-looking projection.
Salary, freelance deposits, and allowances are placed on the dates they land so the monthly spending plan mirrors cash availability.
Rent, loans, insurance, and tuition are reserved before discretionary categories receive targets.
Food, fuel, and household supplies receive ranges — not single numbers — so normal variance does not feel like failure.
Consultations end with a short checklist for the next 30 days: what to watch, what to defer, and when to reconvene.
No. Work is delivered through financial planning consultations and personalized planning conversations about your household ledgers and habits.
Engagements center on household budgeting and monthly spending plans — categorization, cash timing, and spending guardrails — not securities selection.
Planning is arranged for clients in Bangkok with meetings coordinated from our Sukhumvit office; format and fees are confirmed when you inquire.
Recent bank statements, recurring bill amounts, and any existing budget notes help us start with facts rather than guesses.
Tell us about your household size, pay rhythm, and the monthly spending pressure you want to address.